Large Commercial Property Rates Drop 14.5% in Q2 to Highlight Latest Willis Report
Commercial property rates continues to soften, according to a new report from Willis, a WTW business.
Large and complex property rates with WTW’s portfolio dropped 14.5% in the second quarter 2026, according to the fall 2026 edition of its Insurance Marketplace Realities report. This is compared to a decline in rates of 8.4% during the same time a year ago.
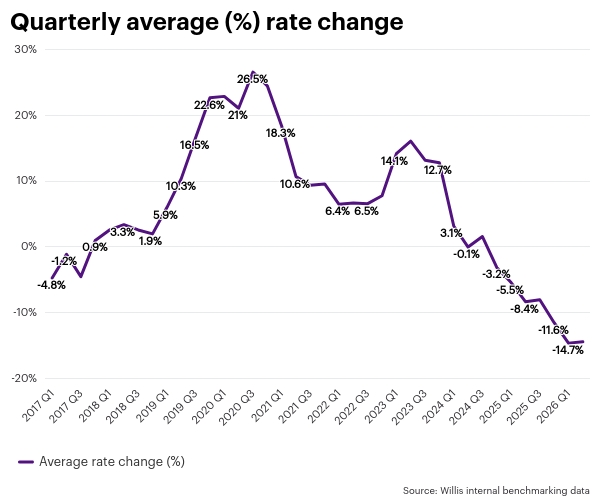
Shared a layer programs with five or more carriers involved saw reductions during Q2 2026 of about 23.4%.
WTW also reported softening treaty reinsurance renewals, signaling abundant primary capacity. Additionally, catastrophe losses for the first half 2026 were $42 billion – the lowest total since 2020.
“The market trajectory has clearly reversed from the challenging period spanning Q1 2018 through Q1 2024,” the broker said.
[inline-ad-1]
The report examines dozens of lines of commercial business in North America.
Of note, cyber rates are holding between a 5% decrease and a 5% increase. Despite increases in risk, market conditions are favoring buyers. WTW advises clients to reinvest insurance savings into higher limits.
Ransomware has maintain its position as a leading driver of losses, and artificial intelligence is increasing cyber risk as it provides businesses with opportunities to improve efficiency and quicken decision-making.
“Buyers may still have the opportunity to enhance their insurance programs through 2026, although signs of rate moderation are emerging across certain cyber insurers and classes of business,” said Willis.
Rate increases in casualty are generally moderating, the report highlighted. Willis said “severity loss trends, social inflation and litigation risks continue to drive disciplined underwriting, higher retentions and strategic program design,” but competition and capacity are improving.
“Signs of greater market stability are emerging as rate increases slow and predictability improves for buyers,” the broker added. “However, underwriting discipline and selective capacity deployment remain key market characteristics.”